International Journal of Coercion, Abuse, and Manipulation Volume 6 2023 104
2013 “Tax Preparer,” 2020).
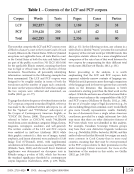
The number of fraudulent tax returns prepared by
Fiscal Arbitrators is unclear. For example, a 2014
media report indicates in 2009 nearly 1,800 taxpayers
employed Fiscal Arbitrators strategies (Hoff, 2014).
A lawyer involved in some Fiscal Arbitrators appeals
claimed the scheme had “up to 3,000” customers
(Melnitzer, 2016). However, at trial, Watts was found
guilty of only preparing false income tax returns for
241 taxpayers. These 241 fraudulent returns attempted
to generate $10,507,131 in evaded taxes and fraudulent
refunds, of which $2,750,288 was actually credited to
taxpayers (R v Watts, 2016 ONSC 4843, paras. 1-2).
The higher volume estimates of Fiscal Arbitrators
income tax returns very plausibly include other related
and unrelated tax avoidance and evasion scheme users.
What can be said with confidence is that a substantial
number of Canadian taxpayers did adopt Fiscal
Arbitrators strategies.
The scope of Fiscal Arbitrators’ activities is plausibly
confused because Fiscal Arbitrators was associated
with other non-pseudolaw questionable income
tax avoidance schemes, in particular charitable gift
programs. These schemes exploited Income Tax
Act provisions that authorize a large tax credit for
donations to charities. Briefly, the charity schemes
either fabricated or greatly multiplied the tax credit
associated with charitable donations (e.g., Canada
(Attorney General) v Nash, 2005 FCA 386 Cannon v
Funds for Canada Foundation, 2012 ONSC 6101 Klotz
v The Queen, 2004 TCC 147 Scott v The Queen, 2010
TCC 237, see also Bozek, 2022).
Reported court decisions show that some Fiscal
Arbitrators customers had previously been involved
in charity-based tax avoidance schemes. For example,
certain Fiscal Arbitrator promoters had first sold charity
schemes, and then introduced their charity scheme
customers to Fiscal Arbitrators to purportedly provide
even further tax advantages (e.g., Lauzon v The Queen,
2016 TCC 71, para. 4 Mayne v The Queen, 2016 TCC
212, paras. 5, 17-24 Wynter v The Queen, 2016 TCC
103, para. 5). A multilevel marketing charity donation
program, DSC Lifestyle Services (“Financial Company
Director,” 2013), is frequently linked to these scenarios.
Another repeating motif is that refunds obtained
by Fiscal Arbitrators would not be recovered by
taxpayers, but instead were immediately directed into
questionable to fraudulent investment schemes, such as
Frieslander Financials (e.g., Brisson v The Queen, 2013
TCC 235, paras. 12, 21 Mallette v The Queen, 2016
TCC 27, paras. 3-5). Friesland Financials reportedly
required its investors only file income tax returns via
Fiscal Arbitrators (Mallette v The Queen, 2016 TCC
27, para. 31). Muntaz Rasool also was involved in pre-
Fiscal Arbitrators investment schemes (e.g., Anderson v
The Queen, 2016 TCC 93, paras. 11-13).
The typical fee structure for Fiscal Arbitrators was an
up-front payment of $500, then 20% of the total refund
received (e.g., Chartrand v The Queen, 2015 TCC 298,
para. 27 Daszkiewicz v The Queen, 2016 TCC 44,
para. 37 Mallette v The Queen, 2016 TCC 27, para.
5), though some taxpayers reported more aggressive
billing, such as an over $10,000 “contingency fee”
(Taylor v The Queen, 2015 TCC 335, para. 40), or that
Rasool had demanded 50% of refunds received from
the CRA (Robichaud v The Queen, 2016 TCC 19, para.
31). Fiscal Arbitrators consistently did not include any
tax preparer information in its customers’ returns,
despite that being required by law.
Fiscal Arbitrators promoters are frequently reported to
have claimed to be former CRA employees:
• Branch (e.g., Gray v The Queen, 2016 TCC 54,
para. 5)
• Danasar Morlee (e.g., Brathwaite v The Queen,
2016 TCC 29, para. 11)
• Rasool (e.g., Hogg v The Queen, 2017 TCC 231,
para. 4 Robichaud v The Queen, 2016 TCC 19,
para. 29) and
• Watts (e.g., Brisson v The Queen, 2013 TCC 235,
para. 9).
This purported subject expertise was, however,
countered by provisos in Fiscal Arbitrators documents,
such as: “all information, material, is strictly for
educational and private purposes,” and that Fiscal
Arbitrators promoters had no legal, tax, or accounting
expertise (Mior v Canada (Attorney General), 2019 FC
321, para. 16).
2013 “Tax Preparer,” 2020).
The number of fraudulent tax returns prepared by
Fiscal Arbitrators is unclear. For example, a 2014
media report indicates in 2009 nearly 1,800 taxpayers
employed Fiscal Arbitrators strategies (Hoff, 2014).
A lawyer involved in some Fiscal Arbitrators appeals
claimed the scheme had “up to 3,000” customers
(Melnitzer, 2016). However, at trial, Watts was found
guilty of only preparing false income tax returns for
241 taxpayers. These 241 fraudulent returns attempted
to generate $10,507,131 in evaded taxes and fraudulent
refunds, of which $2,750,288 was actually credited to
taxpayers (R v Watts, 2016 ONSC 4843, paras. 1-2).
The higher volume estimates of Fiscal Arbitrators
income tax returns very plausibly include other related
and unrelated tax avoidance and evasion scheme users.
What can be said with confidence is that a substantial
number of Canadian taxpayers did adopt Fiscal
Arbitrators strategies.
The scope of Fiscal Arbitrators’ activities is plausibly
confused because Fiscal Arbitrators was associated
with other non-pseudolaw questionable income
tax avoidance schemes, in particular charitable gift
programs. These schemes exploited Income Tax
Act provisions that authorize a large tax credit for
donations to charities. Briefly, the charity schemes
either fabricated or greatly multiplied the tax credit
associated with charitable donations (e.g., Canada
(Attorney General) v Nash, 2005 FCA 386 Cannon v
Funds for Canada Foundation, 2012 ONSC 6101 Klotz
v The Queen, 2004 TCC 147 Scott v The Queen, 2010
TCC 237, see also Bozek, 2022).
Reported court decisions show that some Fiscal
Arbitrators customers had previously been involved
in charity-based tax avoidance schemes. For example,
certain Fiscal Arbitrator promoters had first sold charity
schemes, and then introduced their charity scheme
customers to Fiscal Arbitrators to purportedly provide
even further tax advantages (e.g., Lauzon v The Queen,
2016 TCC 71, para. 4 Mayne v The Queen, 2016 TCC
212, paras. 5, 17-24 Wynter v The Queen, 2016 TCC
103, para. 5). A multilevel marketing charity donation
program, DSC Lifestyle Services (“Financial Company
Director,” 2013), is frequently linked to these scenarios.
Another repeating motif is that refunds obtained
by Fiscal Arbitrators would not be recovered by
taxpayers, but instead were immediately directed into
questionable to fraudulent investment schemes, such as
Frieslander Financials (e.g., Brisson v The Queen, 2013
TCC 235, paras. 12, 21 Mallette v The Queen, 2016
TCC 27, paras. 3-5). Friesland Financials reportedly
required its investors only file income tax returns via
Fiscal Arbitrators (Mallette v The Queen, 2016 TCC
27, para. 31). Muntaz Rasool also was involved in pre-
Fiscal Arbitrators investment schemes (e.g., Anderson v
The Queen, 2016 TCC 93, paras. 11-13).
The typical fee structure for Fiscal Arbitrators was an
up-front payment of $500, then 20% of the total refund
received (e.g., Chartrand v The Queen, 2015 TCC 298,
para. 27 Daszkiewicz v The Queen, 2016 TCC 44,
para. 37 Mallette v The Queen, 2016 TCC 27, para.
5), though some taxpayers reported more aggressive
billing, such as an over $10,000 “contingency fee”
(Taylor v The Queen, 2015 TCC 335, para. 40), or that
Rasool had demanded 50% of refunds received from
the CRA (Robichaud v The Queen, 2016 TCC 19, para.
31). Fiscal Arbitrators consistently did not include any
tax preparer information in its customers’ returns,
despite that being required by law.
Fiscal Arbitrators promoters are frequently reported to
have claimed to be former CRA employees:
• Branch (e.g., Gray v The Queen, 2016 TCC 54,
para. 5)
• Danasar Morlee (e.g., Brathwaite v The Queen,
2016 TCC 29, para. 11)
• Rasool (e.g., Hogg v The Queen, 2017 TCC 231,
para. 4 Robichaud v The Queen, 2016 TCC 19,
para. 29) and
• Watts (e.g., Brisson v The Queen, 2013 TCC 235,
para. 9).
This purported subject expertise was, however,
countered by provisos in Fiscal Arbitrators documents,
such as: “all information, material, is strictly for
educational and private purposes,” and that Fiscal
Arbitrators promoters had no legal, tax, or accounting
expertise (Mior v Canada (Attorney General), 2019 FC
321, para. 16).